Categories
Downsizing, Lifestyle, Home Buying Tips, Market Trends, renting your homePublished September 18, 2026
How to Actually Cut Your Monthly Costs When Everything Feels Expensive
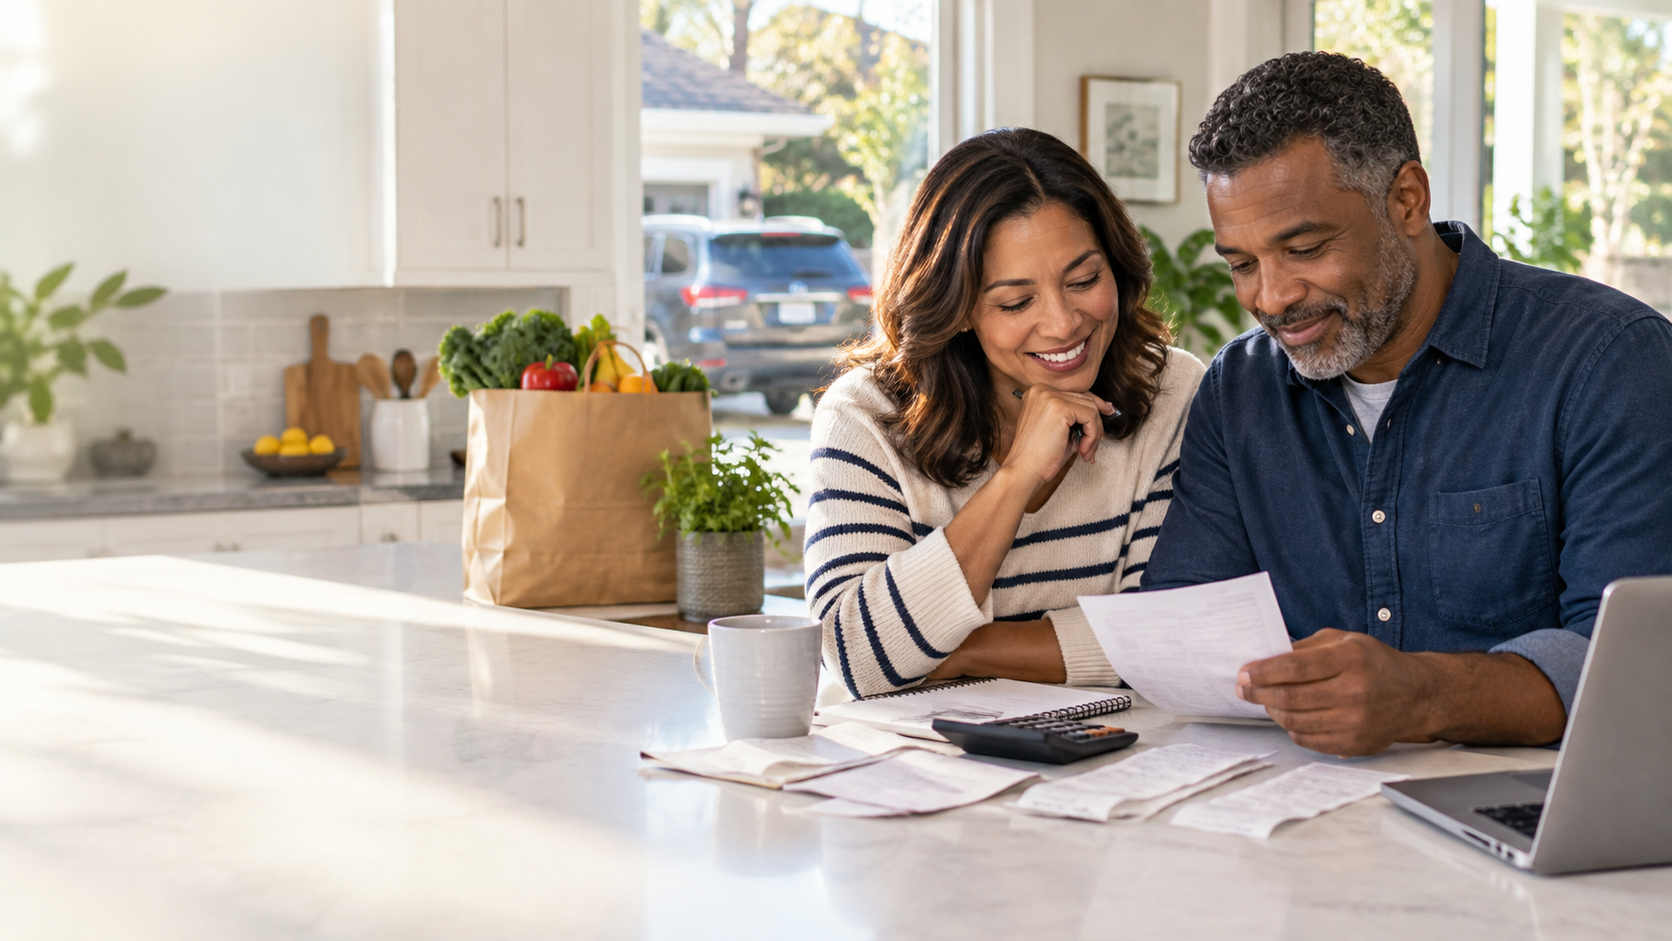
Let's be honest: the budget math isn't working the way it used to.
Gas prices are punishing. Grocery bills have quietly crept up to numbers that still catch people off guard at checkout. Utilities, insurance premiums, childcare- pick a line item and it's probably higher than it was two years ago. And wages, for most people, haven't kept pace.
If you're feeling squeezed, you're not mismanaging your money. You're navigating an economy that's genuinely more expensive than it was and that calls for a different playbook than the one most of us grew up with.
This isn't a post about cutting lattes. These are real, meaningful changes that can add up to hundreds of dollars back in your pocket every month.
Gas prices vary by as much as 30–40 cents per gallon within just a few miles of each other in the Queens and Nassau County area. The GasBuddy app shows you real-time prices at every station nearby. It takes 30 seconds and costs nothing.
2. Use a gas rewards credit card and actually pay it off monthly.
Cards like the Citi Custom Cash or PenFed Platinum Rewards return 3–5% on gas purchases. On $300/month in gas, that's $9–$15 back per month. The catch: this only saves you money if you're paying the balance in full. Carrying a balance erases the benefit immediately.
3. Slow down.
Driving at 65 mph instead of 80 mph can improve fuel efficiency by 15–20%. Most people don't notice the extra few minutes. Their tank does.
For items like canned tomatoes, pasta, rice, frozen vegetables, and cleaning supplies, store-brand products are often manufactured by the same companies as name brands — just with different packaging. Switching 10 items per week can save $30–$50 per month without changing what you eat.
5. Plan your meals around what's on sale.
Most people decide what they want to eat, then buy those ingredients at full price. Flip it: check the weekly circular first, then build your meals around what's marked down. This single habit change routinely cuts grocery bills by 20–30%.
6. Stop throwing food away.
The USDA estimates the average American household throws away roughly $1,500 worth of food per year. That's a car payment. Do a "use it up" dinner once a week where you cook whatever is in the fridge before it turns, and freeze leftovers before they hit the point of no return.
"Vampire power" — electricity drawn by devices in standby mode — accounts for roughly 10% of the average household's electric bill. Smart power strips run about $25 and pay for themselves within weeks.
8. Run your dishwasher and laundry at night.
Off-peak hours typically come with lower electricity rates under time-of-use billing plans. If your utility offers this and you're not on it yet, call and ask. Shifting high-draw appliances to evenings can shave $20–$40 per month off your bill.
9. Check your weatherstripping and insulation.
Drafty windows and doors force your HVAC system to work harder than it should. New weatherstripping costs about $20 at a hardware store and takes an hour. A full attic insulation upgrade can reduce heating and cooling costs by 15–25% annually — and it adds value to your home when you eventually sell.
10. Audit your subscriptions — all of them.
Pull up your credit card statement and highlight every recurring charge. Most people find 3–5 subscriptions they'd forgotten about. Cutting four unused subscriptions at $15–$20 each is $60–$80 back per month — up to $960 per year.
Homeowner's insurance premiums have increased significantly in recent years, and loyalty doesn't pay in this industry. Switching carriers for the same coverage commonly saves $300–$800 per year.
12. Bundle your auto and home insurance.
If they're currently with different carriers, consolidating them typically earns a 10–20% multi-policy discount. Call your current carrier, ask for the bundle rate, then compare it to competitors.
This is one of the most underused cost-saving tools available to homeowners in New York. If your home's assessed value is higher than what it would realistically sell for today, you may be overpaying in taxes. In Nassau County, the process runs through the Assessment Review Commission. In Queens, through the NYC Tax Commission. Both have annual deadlines — don't wait.
A finished basement, an accessory dwelling unit, or a room in your home can generate $1,000–$2,500 per month depending on the area. In Queens and Nassau County, rental demand remains extremely strong. That income can offset a significant portion of your monthly housing costs.
Not sure if your property qualifies or where to even start? We work with a trusted partner who can assess your property, walk you through local zoning requirements, and help you apply for a legal ADU — so you're generating rental income the right way, without the liability of an unpermitted space. It's one of the smartest moves a homeowner can make in this economy.
This one is simple, costs nothing to do, and most homeowners have never thought about it. Instead of making one full mortgage payment per month, you split it in half and pay every two weeks. Because there are 52 weeks in a year, this results in 26 half-payments — which equals 13 full payments instead of 12. That one extra payment per year goes entirely toward your principal balance, not interest.
The impact adds up faster than most people expect. On a 30-year mortgage at today's rates, switching to bi-weekly payments can shave 4–6 years off your loan term and save tens of thousands of dollars in interest over time — without refinancing, without changing your budget dramatically, and without any fees if you set it up directly with your lender. Call your mortgage servicer and ask them to set it up. Most do it for free.
Shop your mortgage rate — aggressively.
Most buyers contact one lender and go with whatever rate they're offered. But mortgage rates can vary by 0.5–1% between lenders on the same loan — which on a $500,000 purchase translates to $150–$300 per month. Get quotes from at least three lenders before you commit to anything.
Ask about down payment assistance programs and grants.
There are more programs available than most buyers realize — and they're not just for first-timers. We work with multiple lending partners who offer a range of down payment assistance programs and grants covering a wide variety of buyer scenarios: income levels, property types, credit profiles, and geographic areas. Many of our buyers have been genuinely surprised by what they qualified for — including grants they never had to pay back.
Negotiate hard on the purchase price.
In the current market, a skilled buyer's agent can make a meaningful difference in what you actually pay. We know which sellers are motivated, which listings have been sitting, and where there's room to negotiate — whether that's price, closing cost contributions, or repair credits. The difference between an average offer and a well-negotiated one can easily be $10,000–$30,000 on a Queens or Nassau County purchase.
What if your home is the solution, not just the problem?
Homeowners across Queens and Nassau County who bought 7, 10, or 15 years ago are sitting on significant equity. And in many cases, selling a larger home and moving into something smaller and more cost-efficient doesn't just reduce monthly expenses — it can generate a lump sum that resets your entire financial picture.
Here's what downsizing can look like in practice:
And if you're a homeowner, renter, or buyer who wants to talk through how real estate fits into your financial picture right now, we're always here for that conversation.
📞 (917) 727-1207
📧 allison@rafaelchingteam.com
🌐 rafaelchingteam.com
Rafael Ching Team | Keller Williams Greater Nassau | Serving NYC, Queens, Brooklyn, Nassau County & Long Island in
Gas prices are punishing. Grocery bills have quietly crept up to numbers that still catch people off guard at checkout. Utilities, insurance premiums, childcare- pick a line item and it's probably higher than it was two years ago. And wages, for most people, haven't kept pace.
If you're feeling squeezed, you're not mismanaging your money. You're navigating an economy that's genuinely more expensive than it was and that calls for a different playbook than the one most of us grew up with.
This isn't a post about cutting lattes. These are real, meaningful changes that can add up to hundreds of dollars back in your pocket every month.
⛽ At the Gas Pump
1. Use GasBuddy religiously.Gas prices vary by as much as 30–40 cents per gallon within just a few miles of each other in the Queens and Nassau County area. The GasBuddy app shows you real-time prices at every station nearby. It takes 30 seconds and costs nothing.
2. Use a gas rewards credit card and actually pay it off monthly.
Cards like the Citi Custom Cash or PenFed Platinum Rewards return 3–5% on gas purchases. On $300/month in gas, that's $9–$15 back per month. The catch: this only saves you money if you're paying the balance in full. Carrying a balance erases the benefit immediately.
3. Slow down.
Driving at 65 mph instead of 80 mph can improve fuel efficiency by 15–20%. Most people don't notice the extra few minutes. Their tank does.
🛒 At the Grocery Store
4. Shop the store brand for staples.For items like canned tomatoes, pasta, rice, frozen vegetables, and cleaning supplies, store-brand products are often manufactured by the same companies as name brands — just with different packaging. Switching 10 items per week can save $30–$50 per month without changing what you eat.
5. Plan your meals around what's on sale.
Most people decide what they want to eat, then buy those ingredients at full price. Flip it: check the weekly circular first, then build your meals around what's marked down. This single habit change routinely cuts grocery bills by 20–30%.
6. Stop throwing food away.
The USDA estimates the average American household throws away roughly $1,500 worth of food per year. That's a car payment. Do a "use it up" dinner once a week where you cook whatever is in the fridge before it turns, and freeze leftovers before they hit the point of no return.
💡 On Your Utilities
7. Unplug devices you're not using."Vampire power" — electricity drawn by devices in standby mode — accounts for roughly 10% of the average household's electric bill. Smart power strips run about $25 and pay for themselves within weeks.
8. Run your dishwasher and laundry at night.
Off-peak hours typically come with lower electricity rates under time-of-use billing plans. If your utility offers this and you're not on it yet, call and ask. Shifting high-draw appliances to evenings can shave $20–$40 per month off your bill.
9. Check your weatherstripping and insulation.
Drafty windows and doors force your HVAC system to work harder than it should. New weatherstripping costs about $20 at a hardware store and takes an hour. A full attic insulation upgrade can reduce heating and cooling costs by 15–25% annually — and it adds value to your home when you eventually sell.
10. Audit your subscriptions — all of them.
Pull up your credit card statement and highlight every recurring charge. Most people find 3–5 subscriptions they'd forgotten about. Cutting four unused subscriptions at $15–$20 each is $60–$80 back per month — up to $960 per year.
🏠 On Your Insurance
11. Shop your homeowner's insurance every renewal cycle.Homeowner's insurance premiums have increased significantly in recent years, and loyalty doesn't pay in this industry. Switching carriers for the same coverage commonly saves $300–$800 per year.
12. Bundle your auto and home insurance.
If they're currently with different carriers, consolidating them typically earns a 10–20% multi-policy discount. Call your current carrier, ask for the bundle rate, then compare it to competitors.
💡 Want a free quote? We work with a trusted insurance partner who shops multiple carriers to find you the best rate on homeowner's and auto coverage. It's free, takes about 10 minutes, and there's zero obligation. Contact us at (917) 727-1207 and we'll make the introduction.
🏡 On Your Home Specifically
13. Appeal your property tax assessment.This is one of the most underused cost-saving tools available to homeowners in New York. If your home's assessed value is higher than what it would realistically sell for today, you may be overpaying in taxes. In Nassau County, the process runs through the Assessment Review Commission. In Queens, through the NYC Tax Commission. Both have annual deadlines — don't wait.
💡 Not sure what your home is worth right now? A current market analysis from a local agent gives you the comparable sales data you need to make a credible tax appeal. It's free to request and takes no commitment. Reach out anytime.14. Consider renting out unused space.
A finished basement, an accessory dwelling unit, or a room in your home can generate $1,000–$2,500 per month depending on the area. In Queens and Nassau County, rental demand remains extremely strong. That income can offset a significant portion of your monthly housing costs.
Not sure if your property qualifies or where to even start? We work with a trusted partner who can assess your property, walk you through local zoning requirements, and help you apply for a legal ADU — so you're generating rental income the right way, without the liability of an unpermitted space. It's one of the smartest moves a homeowner can make in this economy.
💡 Interested in exploring this for your property? Reach out at (917) 727-1207 or allison@rafaelchingteam.com and we'll connect you with our ADU specialist for a free initial assessment.15. Switch to bi-weekly mortgage payments.
This one is simple, costs nothing to do, and most homeowners have never thought about it. Instead of making one full mortgage payment per month, you split it in half and pay every two weeks. Because there are 52 weeks in a year, this results in 26 half-payments — which equals 13 full payments instead of 12. That one extra payment per year goes entirely toward your principal balance, not interest.
The impact adds up faster than most people expect. On a 30-year mortgage at today's rates, switching to bi-weekly payments can shave 4–6 years off your loan term and save tens of thousands of dollars in interest over time — without refinancing, without changing your budget dramatically, and without any fees if you set it up directly with your lender. Call your mortgage servicer and ask them to set it up. Most do it for free.
🔑 For Buyers: This Market Has More Opportunity Than You Think
If rising costs have you wondering whether homeownership is even realistic right now, here's something worth knowing: the right team and the right financing can change the math significantly.Shop your mortgage rate — aggressively.
Most buyers contact one lender and go with whatever rate they're offered. But mortgage rates can vary by 0.5–1% between lenders on the same loan — which on a $500,000 purchase translates to $150–$300 per month. Get quotes from at least three lenders before you commit to anything.
Ask about down payment assistance programs and grants.
There are more programs available than most buyers realize — and they're not just for first-timers. We work with multiple lending partners who offer a range of down payment assistance programs and grants covering a wide variety of buyer scenarios: income levels, property types, credit profiles, and geographic areas. Many of our buyers have been genuinely surprised by what they qualified for — including grants they never had to pay back.
Negotiate hard on the purchase price.
In the current market, a skilled buyer's agent can make a meaningful difference in what you actually pay. We know which sellers are motivated, which listings have been sitting, and where there's room to negotiate — whether that's price, closing cost contributions, or repair credits. The difference between an average offer and a well-negotiated one can easily be $10,000–$30,000 on a Queens or Nassau County purchase.
💡 Thinking about buying? Let's connect you with one of our lending partners to explore what programs you qualify for — including grants you may never have to pay back. No pressure, just clarity. Call or text (917) 727-1207 or email clientcare@rafaelchingteam.com.
📦 For Sellers: Could Downsizing Actually Put Money Back in Your Pocket?
If your housing costs feel unsustainable right now — high property taxes, utility bills that come with a larger home, maintenance that never seems to end — it may be worth asking a question most people don't think to ask until much later:What if your home is the solution, not just the problem?
Homeowners across Queens and Nassau County who bought 7, 10, or 15 years ago are sitting on significant equity. And in many cases, selling a larger home and moving into something smaller and more cost-efficient doesn't just reduce monthly expenses — it can generate a lump sum that resets your entire financial picture.
Here's what downsizing can look like in practice:
- 💰 Lower mortgage payment — or no mortgage at all, depending on the equity you pull out
- 📋 Lower property taxes on a smaller or less expensive property
- ⚡ Lower utility costs — heating and cooling a smaller space costs meaningfully less
- 🔧 Lower maintenance costs — less square footage, less to maintain, repair, and insure
- 🏦 Freed-up equity that can be invested, used to pay off debt, or simply held as a financial cushion
💡 Thinking about what your home is worth and what a move might look like financially? We can walk you through a side-by-side comparison of your current costs versus what a downsized property would look like — no commitment, no pressure, just numbers. Call (917) 727-1207 to schedule a confidential strategy call.
💭 The Bottom Line
A higher cost of living isn't something you can out-earn your way through overnight. But it is something you can out-strategize, one line item at a time. None of the changes above require you to dramatically alter your lifestyle — they require attention, a little planning, and the willingness to do a few things differently.And if you're a homeowner, renter, or buyer who wants to talk through how real estate fits into your financial picture right now, we're always here for that conversation.
📞 (917) 727-1207
📧 allison@rafaelchingteam.com
🌐 rafaelchingteam.com
Rafael Ching Team | Keller Williams Greater Nassau | Serving NYC, Queens, Brooklyn, Nassau County & Long Island in
English, Spanish & Mandarin
Rafael Ching
Licensed Real Estate Salesperson | Team Leader | Rafael Ching Team at Keller Williams Realty | Queens Real Estate
or another way